Personalized

Mortgage

Solutions

CONTACT ME

About Me

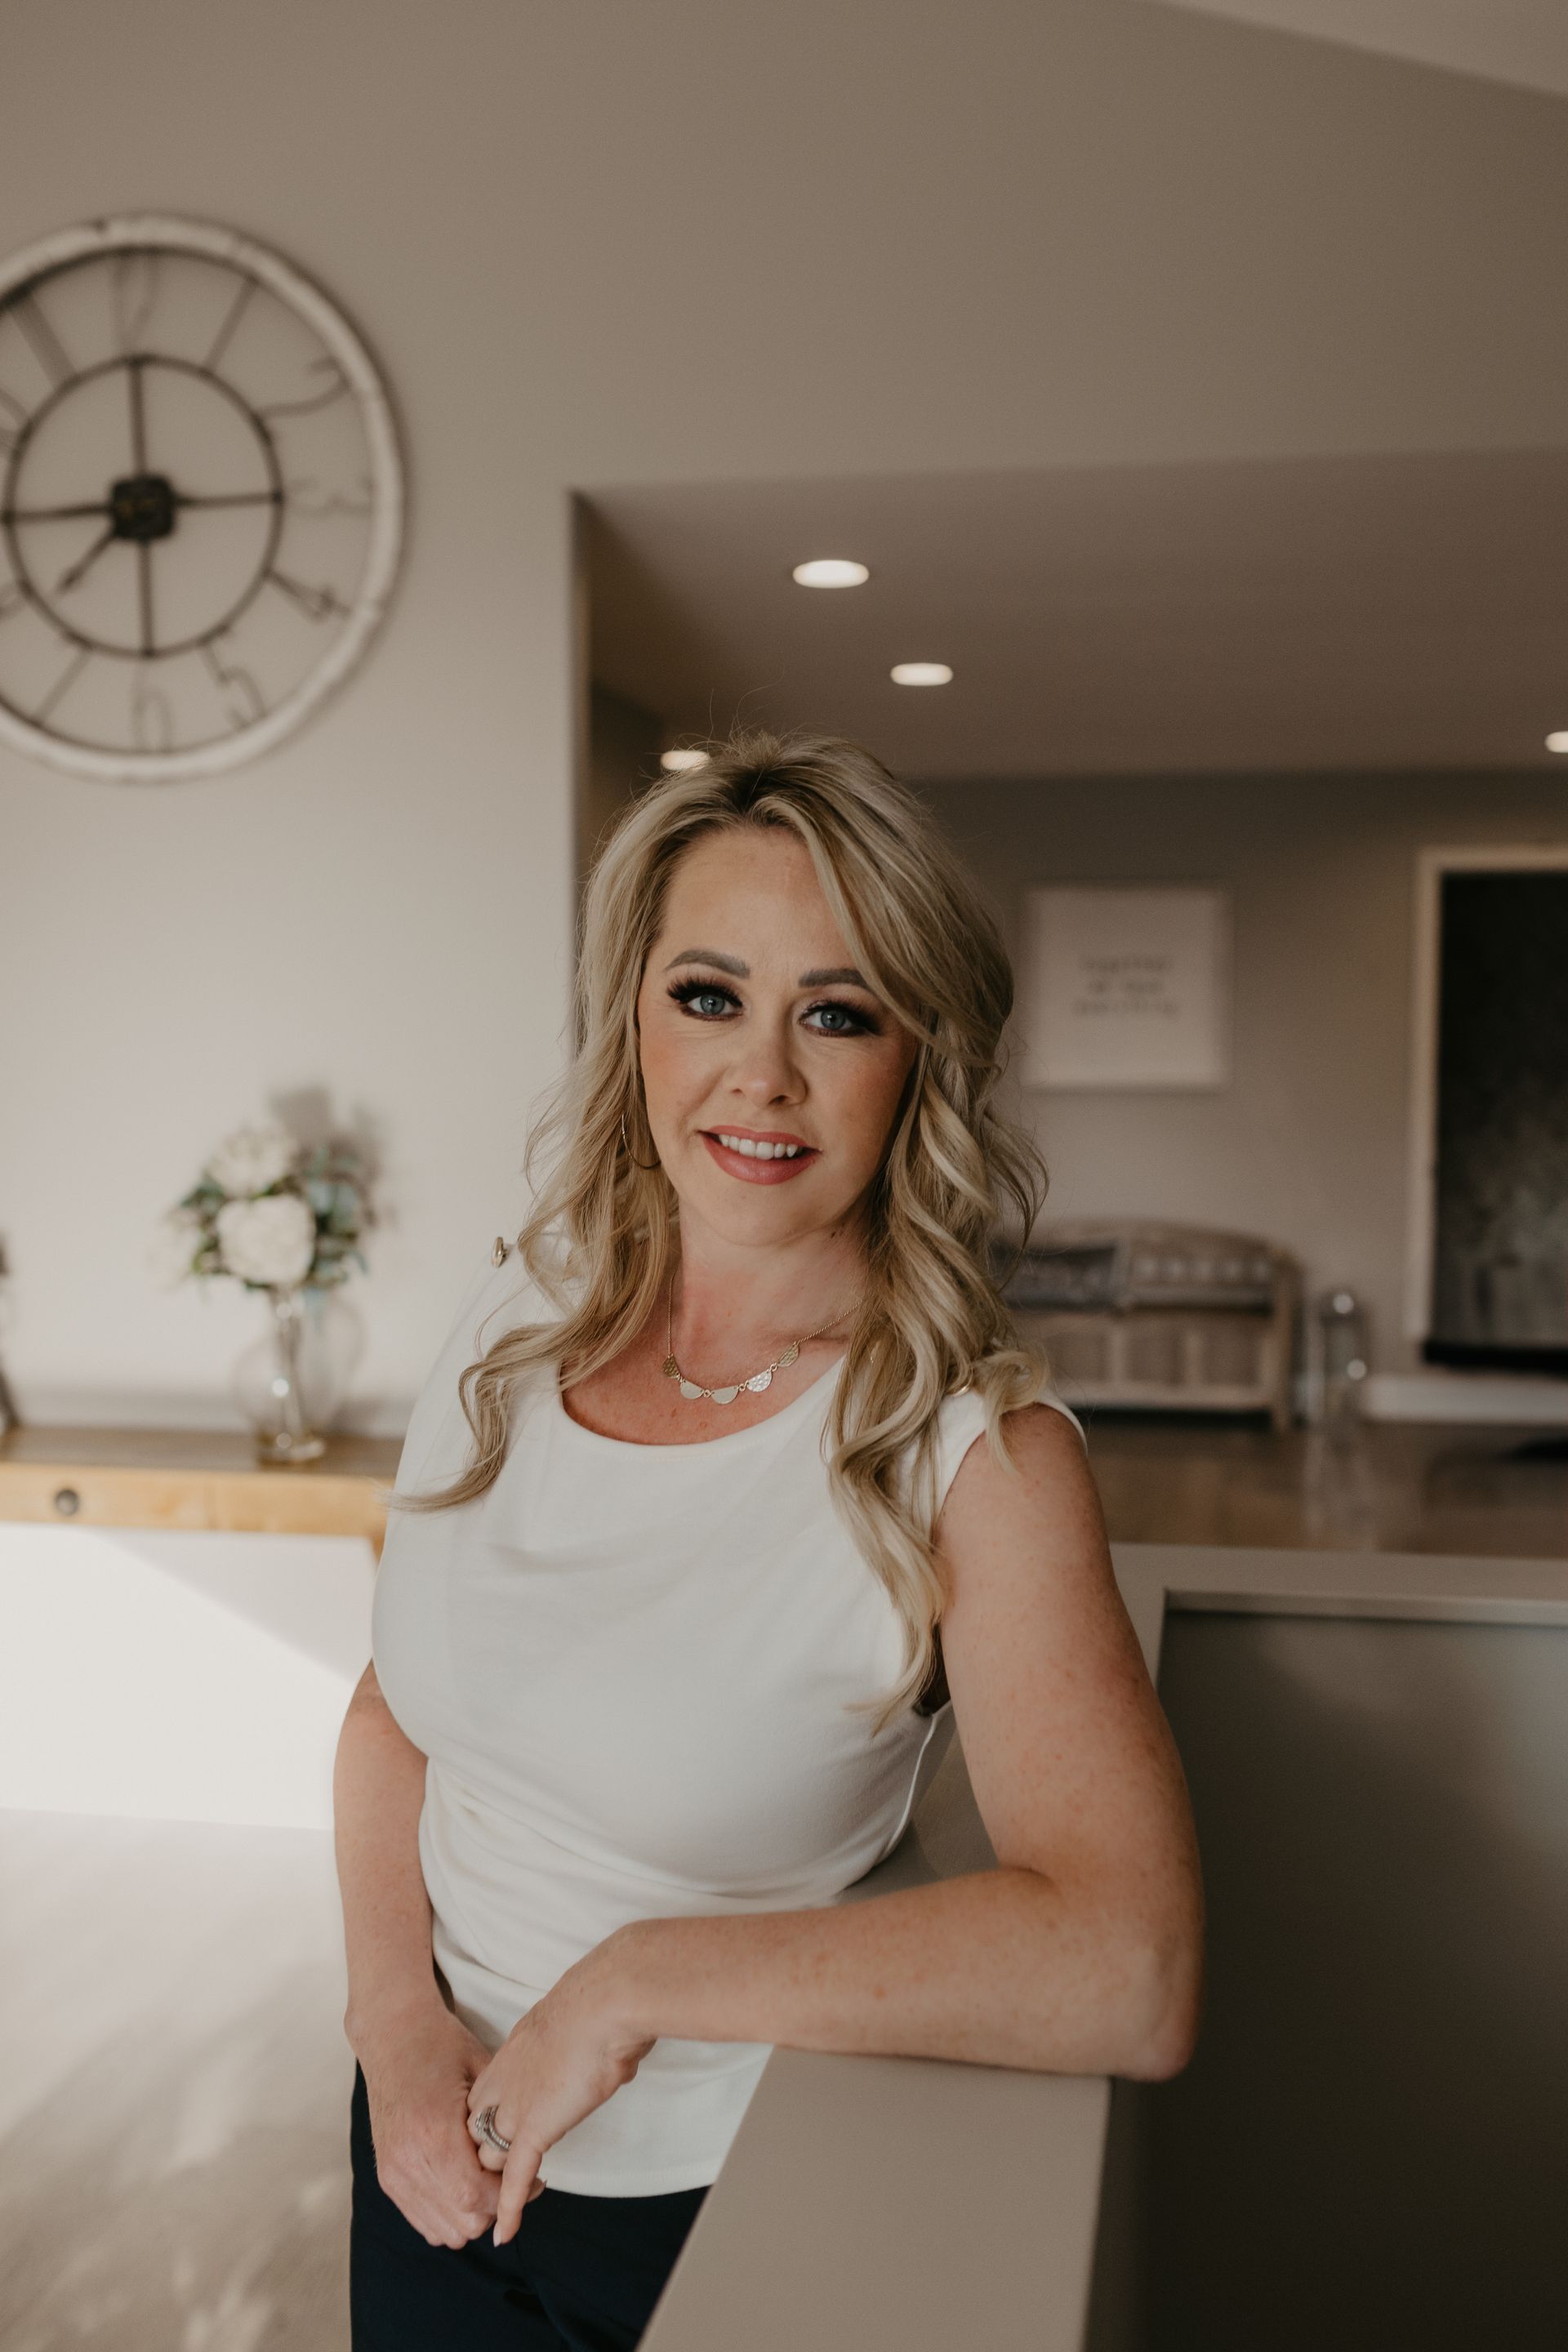
Hi, I’m Angela Campbell (formerly Creed). I’ve practically grown up in the mortgage brokering industry, as I set out on this career path at just 21 years old. Before beginning to build and manage my own mortgage business, I honed my skills in a variety of roles within the industry, including payroll, human resources management, event coordination, client care and mortgage underwriting. This gave me the inside scoop on all angles of the mortgage financing process – from gathering information and fulfilling conditions to deal completion and beyond.


I’m passionate about working with all types of clients, but I have a soft spot for first-time buyers, as they’re so excited about owning their own place, and I love helping turn their home dreams into reality.


But, my job isn’t over once a mortgage has funded. It’s my goal to be with you throughout your time as a mortgage holder, continually adjusting your financing to meet your unique needs.


I’ve personally owned several homes as well as a rental property, so I have first-hand knowledge that provides me with special insight into walking clients through each purchase, and helping navigate the renewal and refinancing processes.


I also know what it’s like to raise a family and make adjustments along the way as life happens – whatever it takes to accommodate an evolving household. I have a toddler and two step children who are heavily involved in soccer and hockey, plus two little dogs I also treat like kids.


My mornings are always spent at the gym or doing yoga before I start my day, so I can clear my mind and rejuvenate myself to take on your mortgage needs – regardless of whether you’re purchasing a new home or renewing/refinancing an existing mortgage.

Services

First Time Home Buyer

First time buyer? This process can be confusing, scary, and downright emotional at times - but it doesn't have to be. 
If you find yourself wondering how much can I afford? How much do I need to put down? How does my credit score effect my purchasing power? Feel free to reach out and let me help walk you through the process of pre-approval to home ownership. 

Home Purchase

If you are looking to purchase a property, understanding all the mortgage options available to you can seem overwhelming. The market is hot and having a clear plan is a must. That’s where I come in, I do this everyday, and I love it. I will help you make sense of all the numbers and provide you with options that make sense to you so you can shop with confidence.

Refinance

Are you looking to refinance your property to access some of the equity built up in your property? Maybe you want to consolidate some debts, start a new business, buy a vacation or investment property… regardless of the reason, I will discuss all your mortgage refinancing options with you and help you to secure the best mortgage available on the market.

Renewal

The best time to start looking at renewing your existing mortgage is 120 days before your maturity date. If your existing lender has sent you a renewal offer in the mail, the first thing you should do is send it to me so I can give you a second opinion. Never just sign the offer, there is always room to negotiate. I am here to help you, so that you don’t have to do those negotiations alone!


Are you looking to buy a new home, refinance, or renew an existing mortgage?

APPLY NOW

Calculators

Curious about what you might be able to afford?

Just getting started?

Find out how much you can afford in 30 seconds.

CALCULATE

Have a specific home in mind?

Find out if you can afford it in 30 seconds.

CALCULATE

Want to refinance a home you own?

Find out how much you can take out in 30 seconds.

CALCULATE

Articles to keep you informed

By Angela Campbell • October 1, 2026
For most Canadians, buying a home isn’t possible without a mortgage. And while getting a mortgage may seem straightforward—borrow money, buy a home, pay it back—it’s the details that make the difference. Understanding how mortgages work (and what to watch out for) is key to keeping your borrowing costs as low as possible. The Basics: How a Mortgage Works A mortgage is a loan secured against your property. You agree to pay it back over an amortization period (often 25 years), divided into shorter terms (ranging from 6 months to 10 years). Each term comes with its own interest rate and rules. While the interest rate is important, it’s not the only thing that determines the true cost of your mortgage. Features, penalties, and flexibility all play a role—and sometimes a slightly higher rate can save you thousands in the long run. Key Questions to Ask Before Choosing a Mortgage How long will you stay in the property? Your timeframe helps determine the right term length and product. Do you need flexibility to move? If a work transfer or lifestyle change is possible, portability may be important. What are the penalties for breaking the mortgage early? This is one of the biggest factors in the real cost of borrowing. A low rate won’t save you if breaking costs you tens of thousands. How are penalties calculated? Some lenders use more borrower-friendly formulas than others. It’s not easy to calculate yourself—get professional help. Can you make extra payments? Prepayment privileges allow you to pay off your mortgage faster, potentially saving years of interest. How is the mortgage registered on title? Some registrations (like collateral charges) can limit your ability to switch lenders at renewal without extra costs. Which type of mortgage fits best? Fixed, variable, HELOCs, or even reverse mortgages each have their place depending on your financial and life situation. What’s your down payment? A larger down payment could reduce or eliminate mortgage insurance premiums, saving thousands upfront. Why the Lowest Rate Isn’t Always the Best Choice It’s tempting to chase the lowest rate, but mortgages with rock-bottom pricing often come with restrictive terms. For example, saving 0.10% on your rate may put a few extra dollars in your pocket each month, but if the mortgage has harsh penalties, you could end up paying thousands more if you break it early. The goal isn’t just the lowest rate—it’s the lowest overall cost of borrowing . That’s why it’s so important to look beyond the headline number and consider the whole picture. The Bottom Line Mortgage financing in Canada is about more than rate shopping. It’s about aligning your mortgage with your financial goals, lifestyle, and future plans. The best way to do that is to work with an independent mortgage professional who can walk you through the fine print and help you secure the product that truly keeps your costs low. If you’d like to explore your options—or review your current mortgage to see if it’s really working in your favour—let’s connect. I’d be happy to help.
By Angela Campbell • September 17, 2026
Co-Signing a Mortgage in Canada: Pros, Cons & What to Expect Thinking about co-signing a mortgage? On the surface, it might seem like a simple way to help someone you care about achieve homeownership. But before you sign on the dotted line, it’s important to understand exactly what co-signing means—for them and for you. You’re Fully Responsible When you co-sign, your name is on the mortgage—and that makes you just as responsible as the primary borrower. If payments are missed, the lender won’t only go after them; they’ll come after you too. Missed payments or default can damage your credit score and put your financial health at risk. That’s why trust is key. If you’re going to co-sign, make sure you have a clear picture of the borrower’s ability to manage payments—and consider monitoring the account to protect yourself. You’re Committed Until They Can Stand Alone Co-signing isn’t temporary by default. Even once the initial mortgage term ends, you won’t automatically be removed. The borrower has to re-qualify on their own, and only then can your name be taken off. If they don’t qualify, you stay on the mortgage for another term. Before agreeing, talk openly about expectations: How long might you be on the mortgage? What’s the plan for eventually removing you? Having these conversations upfront prevents surprises later. It Affects Your Own Borrowing Power When lenders calculate your debt service ratios, the co-signed mortgage counts as your debt—even if you never make a payment on it. This could reduce how much you’re able to borrow in the future, whether it’s for your own home, an investment property, or even refinancing. If you see another mortgage in your future, you’ll want to consider how co-signing could limit your options. The Upside: Helping Someone Get Ahead On the positive side, co-signing can be life-changing for the borrower. You could be helping a family member or friend buy their first home, start building equity, or take an important step forward financially. If handled with clear expectations and trust, it can be a meaningful way to support someone you care about. The Bottom Line Co-signing a mortgage comes with both risks and rewards. It’s not a decision to take lightly, but with careful planning, transparency, and professional advice, it can be done responsibly. If you’re considering co-signing—or want to explore safer alternatives—let’s connect. I’d be happy to walk you through what to expect and help you decide if it’s the right move for you.
By Angela Campbell • September 3, 2026
Thinking About Buying a Second Property? Here’s What to Know Buying a second property is an exciting milestone—but it’s also a big financial decision that deserves thoughtful planning. Whether you're dreaming of a vacation retreat, building a rental portfolio, or looking to support a family member with a place to live, there are plenty of reasons to consider a second home. But before you jump in, it's important to understand the strategy and steps involved. Start with “Why” The best place to begin? Clarify your motivation. Ask yourself: Why do I want to buy a second property? What role will it play in my life or finances? How does this fit into my long-term goals? Whether your focus is lifestyle, income, or legacy planning, knowing your “why” will help you make smarter decisions from the start. Talk to a Mortgage Expert Early Once you’ve nailed down your goals, the next step is to sit down with an independent mortgage professional. Why? Because buying a second property isn't quite the same as buying your first. Even if you’ve qualified before, financing a second home has unique considerations—especially when it comes to down payments, debt ratios, and how lenders assess risk. How Much Do You Need for a Down Payment? Here’s where the purpose of the property really matters: Owner-occupied or family use: You may qualify with as little as 5–10% down, depending on the property and lender. Income property: Expect to put down 20–35%, especially for short-term rentals or if it won’t be occupied by you or a family member. Your down payment amount can be one of the biggest hurdles—but with strategic planning, it’s often manageable. Ways to Fund the Down Payment If you don’t have the full amount in cash, you might be able to tap into your current home’s equity to help fund the purchase. Here are a few ways to do that: ✅ Refinance your existing mortgage to access additional funds ✅ Secure a second mortgage behind your current one ✅ Open a HELOC (Home Equity Line of Credit) ✅ Use a reverse mortgage (in certain age-qualified scenarios) ✅ Take out a new mortgage if your current home is mortgage-free These options depend on your income, credit, home value, and overall financial picture—another reason why having a pro in your corner matters. Second Property Strategy: It’s More Than Just Numbers This purchase should be part of a bigger financial plan—one that balances risk and reward. It’s about: Assessing your full financial health Maximizing your existing assets Minimizing your cost of borrowing Aligning your purchase with your long-term goals Ready to Take the Next Step? There’s no one-size-fits-all answer when it comes to buying a second property. That’s why it helps to talk things through with someone who understands both the big picture and the small details. If you’re ready to explore your options and build a plan to make that second property dream a reality, let’s connect. I’d love to help you take the next step with confidence.
READ MORE

Happy Clients